Retreaded tractor tyres: Lower GST from 1 November 2026
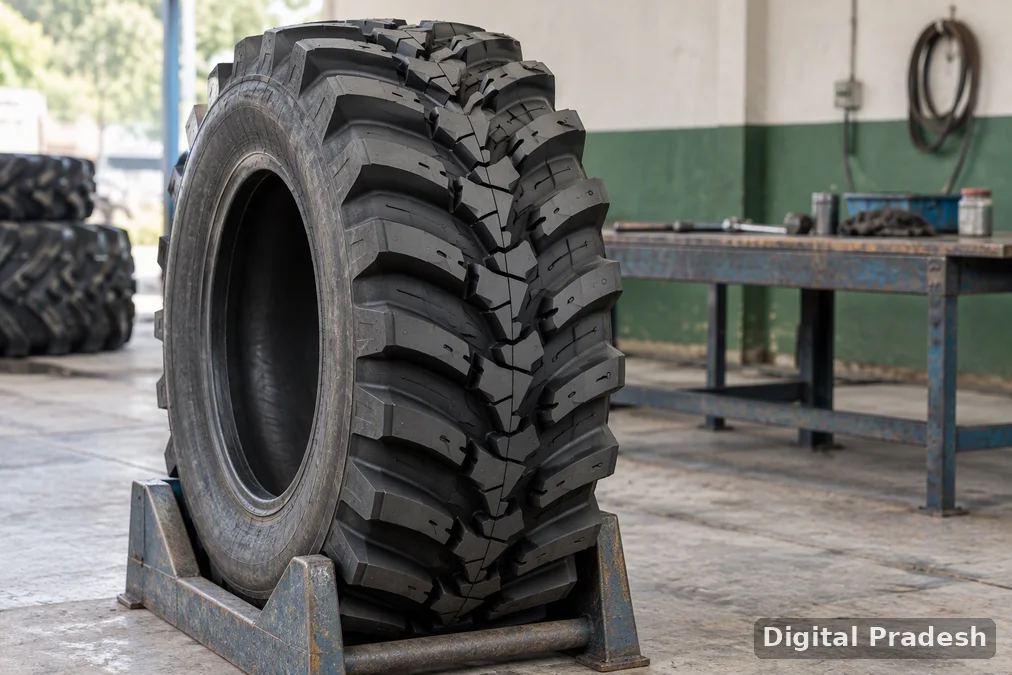
Retreaded tractor tyres will enter the 2.5% central and Union territory tax schedules and the 5% integrated tax schedule from 1 November 2026, while the fertiliser entry will expressly include specified registered seaweed bio-stimulants.
In this article
Listen to this article
The Centre has added retreaded tractor tyres to the lower Goods and Services Tax (GST) rate schedules from 1 November 2026, through Ministry of Finance notifications dated 27 October 2026. The Department of Revenue’s amendments place the goods in Schedule I at 2.5 per cent under central tax and Union territory tax, and 5 per cent under integrated tax.
The same notifications revise a fertiliser entry to expressly include specified seaweed-extract-based bio-stimulants registered under the Fertiliser (Inorganic, Organic or Mixed) (Control) Order, 1985. Both changes have been notified with a future commencement date; their publication on 27 October does not bring them into force immediately.
The ministry issued the amendments through Notification No. 02/2026 in each of the Central Tax (Rate), Integrated Tax (Rate) and Union Territory Tax (Rate) series. They were published in the Gazette of India as G.S.R. 921(E), G.S.R. 922(E) and G.S.R. 923(E), respectively.
A separate entry for retreaded tractor tyres
Each notification inserts serial number 272A, with the goods classification code 4012 and the description “Retreaded tractor tyres”, after serial number 272 in Schedule I. A rate schedule groups specified goods under a stated tax rate; the new entry therefore identifies both the product covered and its place in that schedule.
The ministry has also rewritten serial number 138 in Schedule II to exclude retreaded tractor tyres from the broader tyre entry. This accompanies the insertion in Schedule I, rather than leaving the product named within both rate categories.
Under the replacement wording, Schedule II covers other retreaded or used pneumatic tyres of rubber, along with solid or cushion tyres, tyre treads and tyre flaps of rubber. Pneumatic tyres are air-filled tyres. The Schedule II rates stated in the notifications are 9 per cent for central tax and Union territory tax, and 18 per cent for integrated tax.
The exception is product-specific. The ministry’s wording excludes retreaded tractor tyres, not all retreaded tyres or every rubber tyre product. The other goods listed in the replacement entry remain within its scope.
The different percentages also belong to different tax instruments. The 2.5 per cent figure is the rate specified in the central tax schedule, not the integrated tax rate. The ministry’s integrated tax notification separately places the new entry in its 5 per cent schedule.
Fertiliser entry includes registered seaweed bio-stimulants
The Department of Revenue has replaced the description against serial number 237 in Schedule I across the same three notifications. The replacement covers pre-packaged and labelled animal or vegetable fertilisers, or organic fertilisers.
An explanation attached to that description expressly includes seaweed-extract-based bio-stimulants registered under Schedule VI to the Fertiliser (Inorganic, Organic or Mixed) (Control) Order, 1985. The notification uses that registration reference to specify which bio-stimulants fall within the entry.
The wording does not extend the express inclusion to every product described as a bio-stimulant. It identifies the seaweed-extract-based category and links it to registration under the named control order. The main entry also contains the qualification that the fertilisers are pre-packaged and labelled.
Unlike the tractor tyre amendment, which creates a separate serial number, the fertiliser amendment substitutes the description within an existing entry. The ministry has thus used two different mechanisms: a new product entry for the tyres and revised wording, with an explanation, for the fertilisers.
Amendments to the September 2025 schedules
According to the ministry’s Gazette notifications, the changes amend the corresponding Notification No. 9/2025 rate schedules dated 17 September 2025. The notes accompanying the amendments identify Notification No. 01/2026, dated 30 April 2026, as the previous amendment in each series.
The central tax notification invokes Section 9(1) and Section 15(5) of the Central Goods and Services Tax Act, 2017. The integrated tax instrument cites Section 5(1) of the Integrated Goods and Services Tax Act, 2017, together with Section 15(5) of the central Act.
For Union territory tax, the ministry cites Section 7(1) of the Union Territory Goods and Services Tax Act, 2017, and the same provision of the central Act. These are the statutory provisions the government identifies as its authority for issuing the schedule amendments.
All three instruments state that the Centre acted on the Council’s recommendations. Separately, the Ministry of Finance’s account of the 57th GST Council meeting records that it was held in New Delhi on 8 October 2026, chaired by Union Finance and Corporate Affairs Minister Nirmala Sitharaman. The ministry said that meeting covered process reforms as well as clarifications on selected goods and services.
The Council’s recommendations and the subsequent notifications are distinct documents. For the tyre and fertiliser entries covered here, the operative wording and commencement date are set out in the Gazette amendments.
A separate notification in the same Gazette issue, No. 03/2026-Central Tax (Rate), also adds isabgol seeds under classification code 1211 90 13 to the central tax exemption schedule. The Department of Revenue places that product at serial number 87A and makes the insertion effective from 1 November 2026.

Please log in to leave a comment.


